Kensington and Chelsea · Greater London
Subsidence insurance claim repairs in Kensington and Chelsea
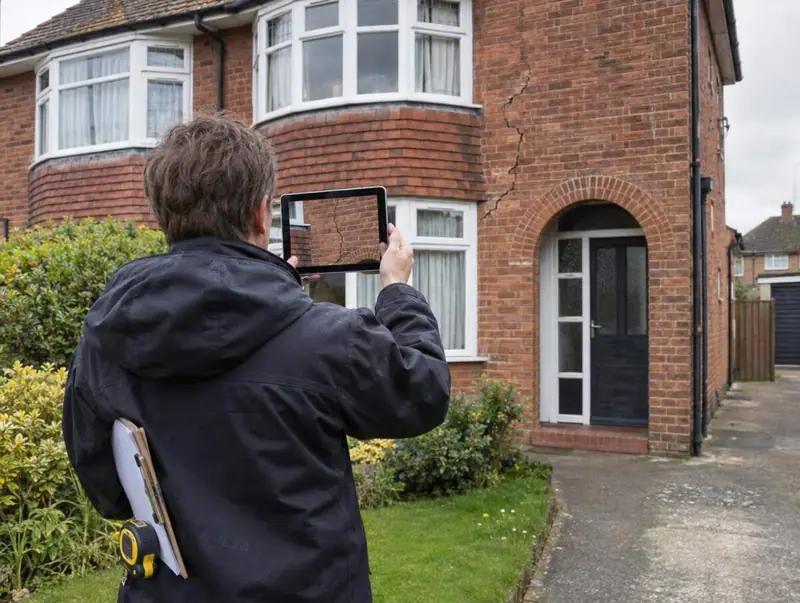
Most subsidence claims for Kensington and Chelsea properties end in crack repairs and redecoration rather than underpinning. Once the cause is dealt with and monitoring shows the house is stable, the schedule of repairs is often fairly modest.
- Postcodes
- SW3, SW5, SW7, SW10, W2
- Population
- about 140,000
- Area
- Greater London
- Pricing region
- London
What should you know about the ground under Kensington and Chelsea?
We cover the whole of Kensington and Chelsea, including postcode districts SW3, SW5, SW7, SW10, W2; about 140,000 people live in the borough. Nearby, we also cover Hammersmith and Fulham (1 miles), Westminster (2 miles) and Wandsworth (3 miles).
Much of Greater London sits on clay that shrinks in dry summers and swells in wet winters. Ground movement here is more often linked to soils, drains and trees than to mining. Housing stock in Greater London: Victorian and Edwardian terraces with shallow footings, inter-war semis in the outer boroughs, and converted flats and mansion blocks.
How we usually approach subsidence insurance claim repairs
Carrying out the agreed repairs
Once the scope is agreed and you instruct us, we carry out the repair, which is often crack stitching, repointing, replastering and redecoration, and sometimes drain or foundation work. We deal with building control where the work needs it and keep the adjuster informed.
Best for: Claims where the repair scope has been settled
Pricing the adjuster’s or engineer’s schedule
When the claim reaches the repair stage, we price the schedule of work line by line, at no charge to request. You or the adjuster can compare it against other prices. The figures follow the agreed scope, so nothing is quietly added or left out.
Best for: Homeowners asked to obtain quotes for an agreed scope
What happens during subsidence insurance claim repairs, step by step?
Notify your insurer
Report suspected subsidence to your buildings insurer as soon as you notice it, with dated photos. Do not start permanent repairs first. Check your schedule for the subsidence excess, which is commonly about £1,000.
Mitigation and monitoring
The identified cause is dealt with, perhaps a drain repair or tree work, and the house may be monitored for several months, sometimes up to 12, to confirm it has stabilised before repairs are agreed.
Repairs and sign-off
With the scope agreed, we carry out the repairs, deal with building control where required and make good. Keep the paperwork, which helps with future insurance and if you sell the house.
What to look for before calling about subsidence insurance claim repairs
- New cracks you think may be caused by ground movement
- You want extra work done while claim repairs are under way
- You have been asked to find your own contractor for the repair
Subsidence insurance claim repairs prices in Kensington and Chelsea
Prices in Kensington and Chelsea are worked out on London rates. They include VAT and are a starting point: access, the extent of the damage and whether an engineer or building control is involved all move the figure.
| Item | Guide price | Per |
|---|---|---|
| Your policy excess for subsidence (check your schedule) | £1,000 | commonly |
| Pricing a loss adjuster's or engineer's repair scheduleest. | Free to request | — |
| Repairs outside the claim (betterment, decoration upgrades)est. | Priced separately | — |
Rules for subsidence insurance claim repairs in England
Like-for-like repairs such as crack stitching and repointing do not usually need building control approval in England, but anything that changes or strengthens the structure, such as underpinning or rebuilding a wall, does. If the work touches a party wall, the Party Wall etc. Act 1996 may apply.
Questions about subsidence insurance claim repairs in Kensington and Chelsea
How much should I budget for subsidence insurance claim repairs in Kensington and Chelsea?
There is no charge for us to price an insurer’s schedule in Kensington and Chelsea. Your fixed written price follows photos or a survey and depends on the extent of the work and access.
Can you survey a property in Kensington and Chelsea?
Yes, Kensington and Chelsea is covered, along with postcode districts SW3, SW5, SW7, SW10. We also cover nearby Hammersmith and Fulham and Westminster.
Why do houses in Greater London crack?
Most of Greater London sits on London Clay, among the most shrinkage-prone ground in the UK, with river gravels along the Thames. Subsidence claims here are among the most frequent in the country, especially after dry summers and near street and garden trees. Only an investigation can say why a particular building has moved.
Will the insurer pay for underpinning?
Only if investigations show it is needed, which is less common than many people expect. Most subsidence claims are fixed by dealing with the cause, such as a drain or tree, and then repairing the cracks. The insurer’s engineer recommends the method.
What if my subsidence claim is declined?
Ask the insurer for the reasons in writing and check them against your policy wording. You can complain to the insurer and then, if unresolved, go to the Financial Ombudsman Service. If you decide to repair privately, we can give a no-obligation written quote.
Related work in Kensington and Chelsea
- Wall tie replacement
- Retaining wall repairs
- Bay window subsidence repairs
- Lintel replacement
- Structural crack repairs
Subsidence insurance claim repairs near Kensington and Chelsea
If your Kensington and Chelsea subsidence claim has been declined, you can still get a no-obligation written quote for a private repair; send photos to start.